Q3 2026: brokers expect rates to hold, and rate rises now outweigh cuts
Among 31 independent mortgage brokers surveyed (25 in French-speaking Switzerland, 6 in German-speaking Switzerland), 61.3% expect the 10-year fixed rate to hold steady over the next 3 months. A rise (32.3%) is now cited five times more often than a cut (6.5%) — a clear break from previous quarters.
1. 10-year fixed vs SARON
Not a single broker expects SARON to fall this quarter — consistent with an SNB policy rate that has been left unchanged.
2. Broker by broker
3. Most requested term
4. Post-SNB recommendation
5. Financing demand vs previous quarter
Financing demand follows the same pattern as rate expectations: more often up (32.3%) than down, with very little contraction (9.7%).
6. What the brokers say
13 of the 31 brokers left an open comment. Here is everything they said — named where they agreed to be, anonymised otherwise.
French-speaking Switzerland (translated from French)
“After several quarters of slowdown, the mortgage market is regaining momentum thanks to lower rates. Clients nevertheless remain demanding and in wait-and-see mode, which intensifies competitive pressure. In this environment, the ability to offer tailored solutions and to guide borrowers effectively is a major growth lever.” — Stéphane Gaspoz, Swiss Life Select
“SARON and 10-year fixed trends differ by property type. SARON is generally preferred for rental properties and the 10-year fixed for owner-occupied homes. During the rate increases in mid-May and mid-July 2026, owner-occupier clients were more inclined to lock in shorter terms (7 years, for example) than to move to SARON.” — Morgan Pauwels, Resolve
“I do not expect any major rate movement over the next three months. The market should stay relatively stable, with fluctuations driven more by international markets than by Swiss monetary policy.” — Fabio Garcia, Monsieur Hypothèque
“Strong correlation with oil and therefore with geopolitical tensions in the Middle East; rates rising abroad, stable but volatile in Switzerland.” — Nicolas Merminod, Flex Advisor
“SARON mortgages remain the most attractive in cost terms, while 5- and 10-year fixed rates are holding around historically moderate levels. Geopolitical tensions and international economic uncertainty could put upward pressure on medium- and long-term fixed rates.” — Independent broker, French-speaking Switzerland
“The Valais market is saturated... it is becoming genuinely very expensive.” — Independent broker, French-speaking Switzerland
“A lot of volatility and uncertainty, and therefore fixed rates that move around a great deal. The spread between the different fixed-rate terms is narrowing.” — Independent broker, French-speaking Switzerland
“Our assessment is that mortgage rates should remain broadly stable over the next three months, with no significant movement in SARON or in 10-year fixed rates. We generally recommend favouring a 10-year fixed mortgage for a family primary residence, in order to lock in housing costs for the long term. The summer period was quiet, with activity picking up since the end of the school holidays. We would stress that this reflects our reading of the market as it stands today, with no certainty as to how geopolitical or monetary events will unfold.” — Independent broker, French-speaking Switzerland
German-speaking Switzerland (translated from German)
“Rate differences between banks remain significant, sometimes between 0.10 and 0.40 points. Clients who compare save a great deal by going through an independent broker.” — Stephan Naef, N2H
“With the policy rate at 0% for a year now, and forecasts holding it there for another year, SARON is currently in very high demand. Splitting (SARON plus fixed) has also become far more attractive. I generally recommend a 50/50 mix, or else 60% fixed and 40% SARON.” — Jason Pfister, Barron Capital
“The cheapest solution is not always the right one for our clients.” — Sheryl Moser, Barron Capital
“Risk appetite varies from bank to bank. Demand for home ownership remains strong. Clients favour flexible term structures so they can react to upcoming tax changes. Renovations are now being actively planned for the next 2.5 years.” — Stéphanie Schellenberg, Kovacs Experience
“Dealing with lenders is becoming increasingly laborious. Good contacts are essential to secure the best financing solutions for the client.” — Jens Behring, Affines
7. The best rate (Swissflex) against the advertised rates of 55 institutions
Beyond broker expectations, two objective data sources complete the picture: the best rate available according to Swissflex, and the advertised rates collected daily from the websites of 55 Swiss banks, insurers and pension funds.
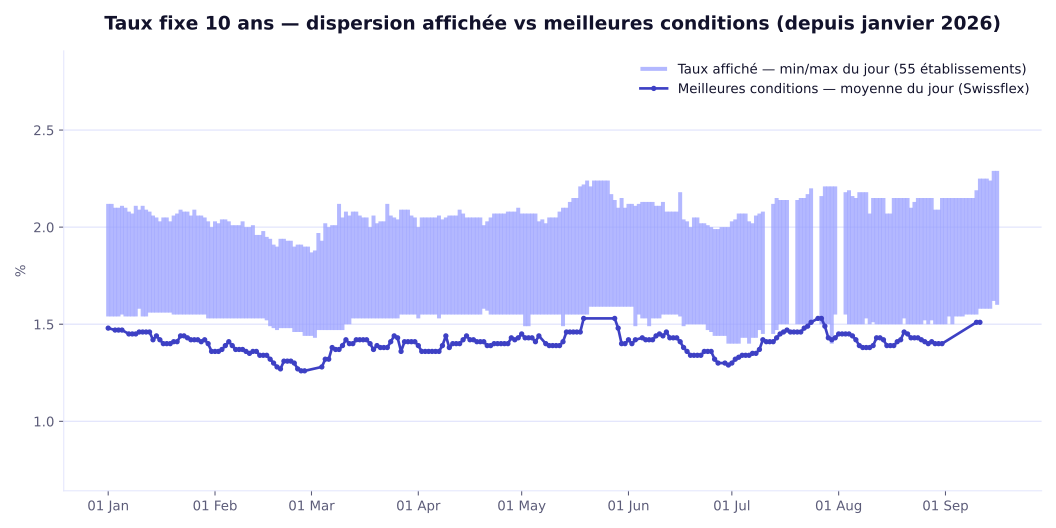
Light band = daily range of advertised rates (min/max across 55 institutions); dark line = best rate available according to Swissflex. The line hugs the lower edge of the band, consistent with a market floor rather than an average.
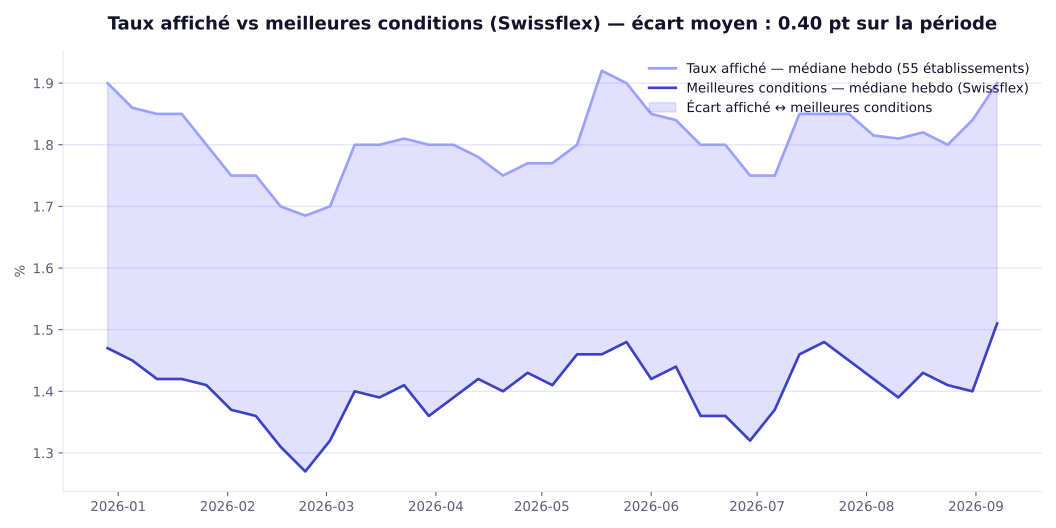
The gap between advertised rates and the best Swissflex rate averages 0.40 points since January 2026 — this is not a one-off spike, it is a structural feature of the market across the whole period.
Methodology
Survey conducted from 12 August to 15 September 2026 among 31 certified independent mortgage brokers partnered with neo-hypotheque.ch (25 in French-speaking Switzerland, 6 in German-speaking Switzerland), representing 43 brokers in total, ahead of the SNB decision of 24 September 2026. Responses aggregated and anonymised.
Who is neo-hypotheque?
neo-hypotheque is an independent mortgage brokerage platform that connects borrowers with a network of more than 50 certified brokers across Switzerland — the same panel that feeds this barometer (31 responses received this quarter). The aim: to let anyone compare, negotiate and secure their property financing without depending on a single bank.
Rates from 55 Swiss banks and insurers are compared continuously, so every offer can be placed against the market.
More than 50 independent brokers, active in both French- and German-speaking Switzerland, support every financing file.
neohypo.com — the first AI agent on WhatsApp for your property search
Once the financing is settled, you still have to find the property. neohypo.com is the first AI agent available directly on WhatsApp to value a property or run a personalised property search in Switzerland — with access to listings never published on the mainstream portals.
Value or search for a property →